• Sort by

  • Industry

Toggle intro on/off

Retail sales for August 2022

Online sales decline

06 October 2022

Australian retail sales rose 19.4% year on year in August 2022. The three-year compound annual growth rate for August was 7.7%, very similar to July 2022 at 8.3%. The most interesting headline is online sales were down 15% year on year, but this largely reflects lockdowns from last year. The three-year online CAGR is still 27%. We expect overall retail sales will remain firm with the first signs of weakness likely in November 2022 given two years of high growth for that month. Retail sales are likely to be softer in 2023 as higher interest rates take effect and savings rates are lower.

Premier Investments FY22 result

Pyjama party almost over

01 October 2022

While Premier Investments reported flat FY22 EBIT, it was a strong 2H22 with EBIT up 23%. The company had very strong second-half sales growth and gross margins expanded. We expect strong sales to persist in 1H23e, but then we are cautious about calendar 2023. Sales growth may turn negative in 2H23e and FY24e on our forecasts even with good growth plans for Peter Alexander. Moreover, wages and rents are likely to be a source of margin compression.

What correlates with retail sales?

The disconnect between sentiment and spending

26 September 2022

In this report, we analyse  consumer sentiment and its role in predicting retail sales. Sentiment has a low correlation with retail spending other than during major crises. While it can help explain the consumer psyche, it doesn’t explain spending. Restaurant and café sales, housing churn, household deposits and food input cost inflation are all far more useful in predicting retail sales in the near-term. The Westpac-Melbourne Institute Consumer Sentiment survey was down 26% in September 2022 compared with long-term trends. Weak sentiment has been evident since March 2022 and contrasts strong retail sales growth.  These indicators are generally favourable with a broader slowdown in retail likely mid 2023. However, household goods categories could slow as soon as October 2022.

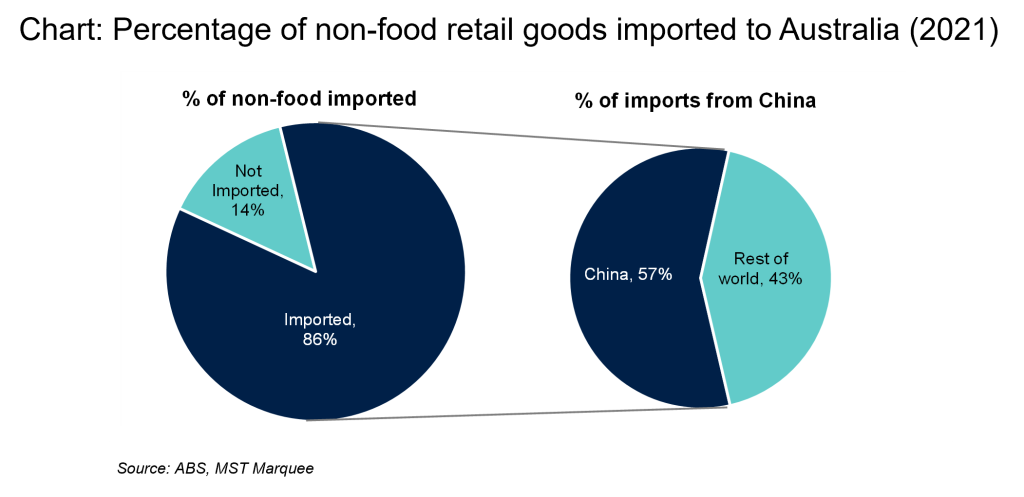
As global trade tensions build and geopolitical risks rise, we think Australian retailers are going to need to diversify their supply chains. Australia imports ~86% of its non-food consumer goods and we estimate 57% of these imports come from China. The productivity of China has led to a concentration of sourcing that represents a real risk on a 5-10 year horizon as Chinese wage rates rise further, supply chains face further disruptions and trade tensions rise. Electronics is the most at-risk category entirely imported, with 56% of imports from China, followed by clothing and accessories at 94% imported, with 55% from China.

Coles Group (COL) Steps away from fuel

Focus on supermarkets and liquor

24 September 2022

Coles has announced the sale of its Fuel & Convenience business to Viva Energy. The company emphasises its desire to focus on its “omni-channel” supermarkets and liquor businesses, as well as become Australia’s most “sustainable” supermarket. The deal is mildly EPS accretive and a decent price for Coles. On our estimates the sale price is 12x EV/EBIT (FY23e) and 0.6% EPS accretive in FY24e. We do see some downside risks over time as Coles may lose the grocery wholesaling business and the cost of fuel discounts may rise.

The Retail Mosaic Issue 4

The role of China in Australian retail - the risks and benefits in offshore sourcing

13 September 2022

Australia is an open economy and over the past twenty years, its retailers have increasingly imported consumer goods. In Issue 4 of The Retail Mosaic, we explore the extent of imports by retail category, the significance of China in supplying goods and exposure various companies have to direct imports from China. China provides the most efficient source of production and for many companies represents more than 70% of their offshore sourcing. The risk is that any increase in costs, supply disruptions or trade tensions could impact sales and margins. The companies sourcing most of their goods from China are Wesfarmers, City Chic, Woolworths, Premier Investments and Super Retail Group.

National accounts for June ’22 quarter

Income growth accelerating

08 September 2022

The National Accounts for the June 2022 quarter paints a strong picture of the  Australian consumer. Despite fears about higher interest rates, the prevailing climate is one where incomes are growing faster and savings are being drawn down gradually. We expect the strength of income and savings to outweigh the headwinds for at least another six months. It is fair to caution that once the slowdown arrives around mid-2023, it could be a protracted downturn.

Retail sales for July 2022

Looking through lockdowns

07 September 2022

Australian retail sales rose 15.8% year on year in July 2022. The three-year compound annual growth rate for July was 8.3%, broadly similar to June 2022 at 7.8%. The year on year growth will be very noisy over July-October given lockdowns from last year. We focus on growth vs 2019 and on that score, recreational goods, apparel, footwear and jewellery had the strongest growth in July 2022. In our view, retail sales will remain firm with the first signs of weakness possible in November 2022. Retail sales are likely to be softer in 2023 given lower household income growth.

Australian supermarkets - The normalisation in supermarkets

Independents holding onto gains

07 September 2022

Australian supermarket industry sales only rose 3% in July 2022. The slowdown is not a reflection of customers retaliating to higher prices, its merely the normalisation from lockdowns last year. In this report, we analyse the likely normalisation path in sales. Coles is likely to grow faster than Woolworths in the September quarter. However, the real winner is Metcash which is holding onto the vast majority of its customer gains. Since 2018, the fundamental shift from the majors to reduce promotions and open fewer stores has provided a better operating environment for Metcash.

Harvey Norman (HVN) FY22 result insights

Precipice may be on the horizon

01 September 2022

Harvey Norman reported a 7% drop in FY22 EBITDA. However, 2H22 EBITDA rose 4% given better sales trends across most divisions. The stronger sales trends are likely to help 1H23e earnings as well. However, the sales environment is likely to be more difficult across calendar 2023 and we forecast earnings to fall. We are also more cautious given Harvey Norman may continue to hold elevated inventory levels.

Search result for "" — 722 articles found

Not already a member?
Join now to get all the latest reports in full and stay informed.

Get started